My Honest, Unfiltered Thoughts On The LSRS – And How To Navigate The Changes
- LSRS is the mandatory global accounting rulebook for land-based emissions and removals. It's here, so we may as well use it – ASAP!
- The heavy lifting is being done by databases and Scope 3 and product footprinting solutions. For downstream food businesses, it really isn't so bad – but check that your tool providers are, in fact, doing what is required!
- Be patient with service providers and suppliers as we make the transition together.
There is no shortage of white papers about the GHG Protocol’s new Land Sector and Removals Standard (LSRS). We even wrote our own client guide at Foodsteps.
So rather than write another summary of the technical text, I wanted to share my unfiltered take as a practitioner of GHG reporting and decarbonisation, as well as someone doing my best to manage an early(ish) stage business that has to adapt to these changes, guide and serve customers through it, and maintain a sustainable business for ourselves.
I write about: what the LSRS actually means for food businesses, what seems scarier than it really is, and what I’d actually do if I were suddenly a sustainability manager
What is the GHG Protocol LSRS? (The 30-Second Test)
If I had to explain the LSRS to my parents (and believe me, I’ve tried) – or to a Board member who just wants the short version (and I’m almost 100% sure that’s what they want) I’d say this:
the LSRS is the global accounting rulebook for emissions from activities related to the land, such as growing food.
Who is Impacted by LSRS: Retailers, Tech, & Food Suppliers
- Tech & Carbon Data Companies: Tech and data companies take on the bulk of the heavy lifting during this transition. It’s expected that we will update databases, calculation models and provide food and agricultural businesses with new emission factors and tech that will handle it. Foodsteps is both a tech and data company, and we’re making updates accordingly.
- Downstream Food Businesses: Retailers, Manufacturers & Food Service: For the most part, these businesses can rely on their tech and data providers to have made the required changes (but do check). In our discussions with upstream data partners (e.g. farm-stage environmental impact calculators), as well as peers, most seem to be making the same changes - so customers won’t need to worry. But please be nice to us while we make this change!
- Upstream Suppliers & Farmers: For the suppliers who already calculate their agricultural footprint or provide it to their downstream customers – know that the structure of what is required, and the underlying details required, has evolved. In many cases, your customers and their data partners will be understanding during this period, but the most advanced downstream businesses are moving quickly to the new standard, and they want their primary data to align.
Measuring & Managing GHGs in an LSRS World: The 5 Steps I’d Take
Changes in standards are incredibly disruptive and I can’t fathom the level of complexity and ambiguity sustainability and scope 3 managers are having to communicate to their stakeholders internally.
I’ve only really sat on the “other side” as a consultant or solutions provider, but if I ever got thrown into the deep end of an internal sustainability role, here’s where I’d start:
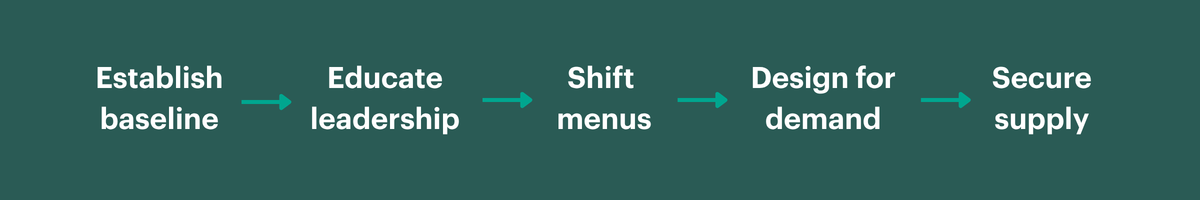
1. Establish or update the baseline to the LSRS (and expect it to change): The standard has evolved, and measuring against an old framework isn’t going to give me the best return on my current, or future time. It’s painful, but I’d make the change as soon as possible.
2. Reinforce that rebaselines are not scary: This might be the slogan I take to a peaceful protest one day. Rebaselining is not a bad thing. It is, in fact, a good thing and is to be expected. I would use the chance of updating to LSRS as a shining example of why rebaselining is needed and reinforce that progress should be assessed on percentage reductions, not the absolute number. Stakeholders need to be brought on this journey.
3. Remain focused on real, actionable decarbonisation shifts: Updated accounting standards change how we measure change but we know – and have known for a while now – many of the most impactful actions we can take. Frameworks like the planetary plate (LINK) have existed for a long time, and action towards designing menus, product portfolios and sales towards this is more impactful, and easier to understand than the complex, shifting world of accounting landscapes and factors. Trust that the accounting will catch up to the real-world change.
4. Drive demand: Sustainability teams need to work and drive change in a commercial environment, where more sustainable, nutritious plates are not necessarily more expensive. At the same time that we improve the supply of what we source, we can – and must – also influence demand. Retailers, brands, and influencers are doing it all the time and pricing, menu or store layouts, and product or packaging design should be part of the toolkit for change.
5. Secure supply through long-term partnerships: The best responses I’ve seen to sustainability data requests are when long-term partnerships with mutual investment are established. Embedding the required data requests is more feasible in such an arrangement, and builds the foundations for – you know it – better data to update my baseline and future year calculations with. It also allows room for product and supply innovation to keep decarbonising core ingredients, or identifying new innovative options.
LSRS Implementation Reality: Is the New Standard Scarier Than It Looks?
It does look scary. The Standard and the Guidance together is over 600 pages long.
I might have read it with a specific lens of, “how do I digest this in the simplest way possible”, but if I keep my sustainability manager hat on, it might be scarier on paper than it is in practice.
If you are working with a food database and platform (shameless plug for Foodsteps here), most of the heavy lifting is done – and other than the very not scary task of rebaselining, the standard and guidance merely provides a framework to improve:
- The level of traceability you can disclose about the food you source – good for transparency and customer engagement and good for business resilience.
- What you know about your food supply, including its impact on the land and land yield. The efficiency of production of your suppliers is a great data point.
- The possibility of reporting removals in your supply chain – an opportunity to evidence great work.
Right now, most people (including me!) are focused on calculating and updating the inventory and new accounting rules. But, somewhere in the 600 pages, the foundations for land sector removals accounting are also established.
I’ll save that for another time though – when I’ve read it in more detail!
Some Final Thoughts
We all knew this was coming. The old guidance was "draft" guidance, after all. But I know how painful it is for teams who only just finished grappling with previous guidance – with many companies still using spend-based Scope 3s.
If the GHGP gods are listening, all I can say is, please let this guidance last. As crucial as it is to refine how we calculate emissions, consistency matters just as much as perfection.
If you’re a sustainability manager, don't try to carry the weight of this guidance on your back alone. Lean on your value chain partners, help your suppliers and your customers navigate the data shift, and let data platforms like ours do what we do best (just give us a bit of time to get there!).
Got questions about where to start or what to do next? Drop our team a line.